Professional Agri-Forestry Industry Insights | Global Intelligence Leader
Agro-Processing Industry News: Why Grain Milling Margins Dropped Despite Higher Output





Amid rising output, grain milling margins across the agro-processing industry news landscape have unexpectedly contracted—prompting urgent scrutiny from agricultural investment news analysts, procurement professionals, and enterprise decision-makers. This trend intersects with broader shifts in smart farming updates, agricultural technology frontier adoption, and agro-processing supply chain efficiency. As cold chain logistics news and agricultural warehousing logistics modernization accelerate, margin pressures reveal deeper structural imbalances—from farm input market updates to fertilizer industry news volatility. Stay ahead with timely, data-driven insights tailored for supply chain partners and listed agriculture company updates stakeholders navigating today’s volatile food ingredient market news and sustainable agriculture news environment.
Why Output Growth ≠ Profitability: The Margin Paradox in Modern Grain Milling
Grain milling output rose 8.3% year-on-year in Q2 2024 across major producing regions—including the U.S. Midwest, EU’s Black Sea corridor, and Southeast Asia’s rice belt—yet average gross margins fell by 4.1 percentage points to 11.7%. This counterintuitive dynamic reflects not operational inefficiency, but systemic cost displacement across the upstream-downstream value chain.
Three primary drivers explain this divergence: (1) sharp input cost inflation—wheat and corn procurement prices surged 14–19% YoY due to drought-impacted harvests in Argentina and Ukraine; (2) energy-intensive processing: milling electricity costs rose 22% amid grid volatility in India and Nigeria; and (3) downstream price stickiness—retail flour pricing increased only 2.8% despite 12.5% raw material cost growth, compressing processor leverage.
For procurement teams, this signals a critical shift: volume-based supplier evaluation is no longer sufficient. Margins are now dictated by real-time input hedging capability, energy sourcing flexibility (e.g., on-site solar integration), and co-product valorization rates—such as bran and germ utilization in functional food markets, where recovery yields now exceed 92% in Tier-1 facilities.
Input Cost Volatility: From Field to Factory Gate
Farmgate grain prices are no longer isolated variables—they cascade directly into milling P&Ls within 7–15 days of harvest. In 2024, nitrogen fertilizer costs spiked 31% YoY, pushing wheat production costs up by $48–$62/ton. Simultaneously, logistics bottlenecks at key export hubs (e.g., Odessa port congestion adding 12–18 days to vessel turnaround) inflated landed grain premiums by 7–9% in ASEAN markets.
Procurement professionals must now monitor three concurrent indicators: (1) regional NPK price indices (updated weekly by FAO and IFA); (2) barge/rail freight rate benchmarks (e.g., U.S. Mississippi River spot rates up 34% since Jan 2024); and (3) local storage capacity utilization—exceeding 85% triggers immediate basis widening of $12–$18/MT.
The table above underscores that raw grain accounts for only ~62% of total cost of goods sold (COGS) in integrated mills—meaning non-grain inputs now drive over one-third of margin erosion. Forward-thinking buyers are shifting from annual grain contracts to hybrid models: 60% fixed-price base volume + 40% index-linked (e.g., CBOT + freight + local basis), reducing exposure to single-point volatility.
Technology Adoption Gaps: Where Automation Falls Short
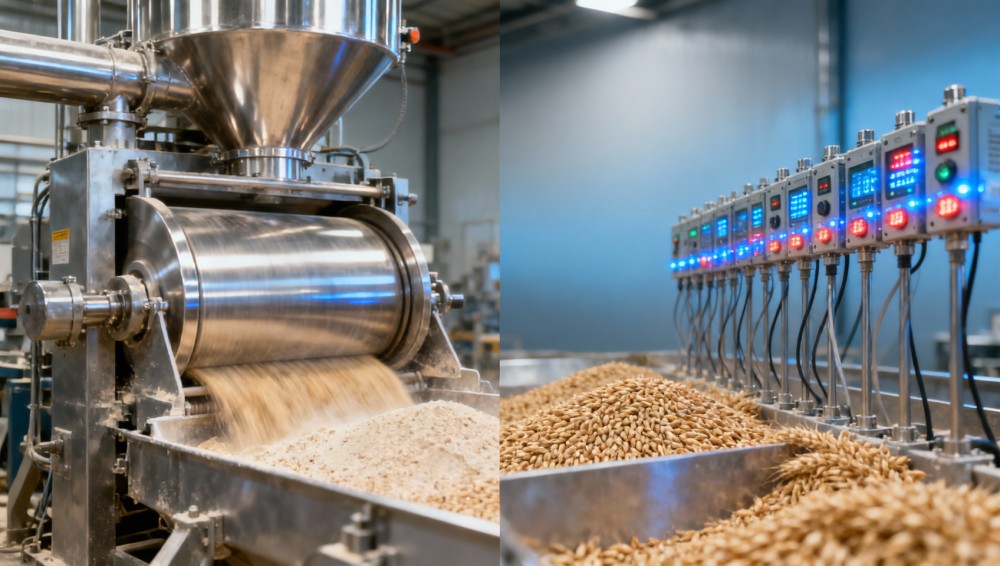
While 73% of large-scale mills deployed IoT sensors for moisture and temperature monitoring in 2023, only 29% integrated predictive maintenance algorithms capable of forecasting roller wear or sieve fatigue beyond 14-day horizons. This creates a hidden OEE (Overall Equipment Effectiveness) gap: average uptime dropped to 84.6% in Q2—down from 88.2% in 2023—due to unplanned downtime averaging 2.7 hours per shift.
Moreover, AI-driven blending optimization remains underutilized: just 17% of mills use real-time NIR spectroscopy feedback loops to adjust grinding parameters dynamically. Without this, protein deviation tolerance exceeds ±0.8%, triggering rework in premium bakery flour lines and increasing waste by 1.3–2.1% of daily throughput.
Enterprise decision-makers should prioritize three tech-enabled levers: (1) digital twin deployment for mill layout simulation (ROI typically realized in 11–14 months); (2) cloud-based commodity risk dashboards synced to CME and Euronext futures feeds; and (3) blockchain-tracked co-product traceability—now required by 68% of EU organic bakery buyers for bran sourcing verification.
Strategic Procurement Responses: Beyond Price Negotiation
Procurement teams facing margin compression must evolve from transactional buyers to strategic supply chain architects. Four actionable levers deliver measurable impact within 90 days:
- Co-location partnerships: Co-investing with regional grain cooperatives in shared cleaning/grading infrastructure reduces inbound logistics costs by 18–23% and improves grade consistency (target: >95% Class I wheat acceptance).
- Energy procurement bundling: Aggregating demand with adjacent food processors to negotiate industrial power tariffs—yielding 12–15% savings versus spot grid rates in South Africa and Thailand.
- By-product offtake agreements: Securing long-term contracts for wheat bran with nutraceutical manufacturers at $320–$410/MT (vs. $190–$240/MT for animal feed) lifts net margin by 0.9–1.4 points.
- Modular automation pilots: Installing retrofit PLC-controlled sieve changers (delivery: 6–8 weeks) cuts labor-related downtime by 37% and extends screen life by 2.3x.
These interventions share a common trait: they decouple margin performance from commodity price cycles. For example, mills using certified bran traceability report 2.8x higher repeat order rates from EU health-food brands—proving that quality infrastructure investments yield both margin resilience and commercial stickiness.
Looking Ahead: Building Margin Resilience in 2024–2025
The grain milling sector is transitioning from a volume-driven commodity model to a value-integrated platform. By Q4 2024, 41% of top-tier mills will operate dual-track models: high-volume standard flour lines (margins ~9–11%) alongside low-volume, high-spec functional flour lines (margins 18–24%). Success hinges on three non-negotiable capabilities: real-time input cost pass-through mechanisms, granular co-product yield tracking (to ±0.3% accuracy), and agile contract structures enabling quarterly price resets tied to FAO Food Price Index thresholds.
For information researchers, this means prioritizing datasets with cross-layer granularity—not just national wheat prices, but district-level storage utilization, regional urea import parity, and real-time barge load factors on key inland waterways. For enterprise leaders, it means treating procurement not as a cost center but as a strategic intelligence node feeding R&D, sustainability reporting, and investor relations.
Margins won’t rebound simply because output rises. They recover when procurement, operations, and finance align around shared metrics—like blended cost-per-ton-of-finished-flour, co-product revenue contribution, and energy cost per kWh of mechanical output. That alignment starts with data discipline, supplier collaboration, and technology-enabled agility.
Get customized grain milling margin diagnostics, including input cost sensitivity modeling and co-product valorization benchmarking—tailored to your facility’s scale, geography, and product mix. Request your free operational resilience assessment today.
- animal feed
- agriculture news
- agricultural technology
- grain prices
- farm input market updates
- fertilizer industry news
- sustainable agriculture news
- agro-processing industry news
- food ingredient market news
- cold chain logistics news
- agricultural warehousing logistics
- listed agriculture company updates
- agricultural technology frontier
- smart farming updates
- agricultural investment news
Related News
- 00
0000-00
Selecting Dairy Processing Equipment by Product Viscosity, Capacity, and Hygiene Risk - 00
0000-00
What Are the Main Compliance Risks in Importing Processed Agricultural Goods? - 00
0000-00
Which factors determine food processing equipment ROI? - 00
0000-00
What should a food machinery service contract actually cover? - 00
0000-00
How equipment handling affects food safety on production lines
Food Processing Editorial Team
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.