Professional Agri-Forestry Industry Insights | Global Intelligence Leader
U.S. Soybean Exports to China Plunge 48.5%, Global Trade Shifts to South America





U.S. Soybean Exports to China Plunge 48.5%, Global Trade Shifts to South America
Introduction
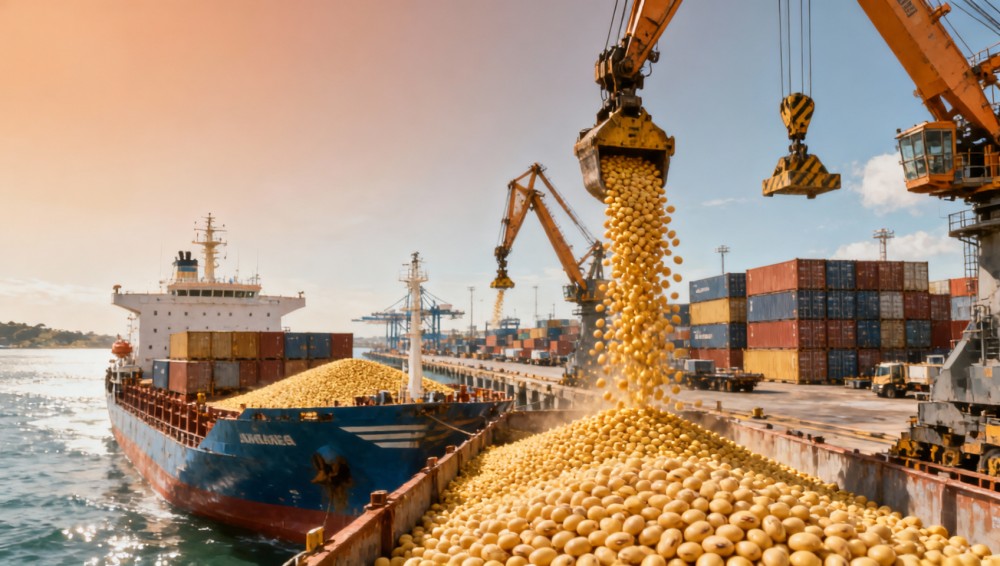
As of March 26, 2026, U.S. soybean exports to China during the 2025/26 season dropped sharply by 48.5% year-on-year to just 11.38 million metric tons. This significant decline coincides with China's increased purchases from Brazil, Argentina, and Ukraine, signaling a major shift in global agricultural trade flows. The changes impact international commodity traders, processing plants, and logistics providers, requiring adjustments to procurement strategies and supply chain configurations.
Event Overview
Customs data shows China's soybean imports from the U.S. fell to 11.38 million metric tons in the 2025/26 marketing year (September-August) as of March 26, 2026, compared to 22.1 million tons during the same period last year. Meanwhile, shipments from Brazil increased by approximately 18%, Argentina by 23%, and Ukraine by 31% year-on-year. The shift reflects China's strategy to diversify agricultural supply sources.
Impact on Key Industries
1. International Commodity Traders
The export decline requires U.S. suppliers to accelerate market diversification beyond China. Traders dealing with South American origins now face tighter competition for limited export volumes, potentially compressing margins. Contracts with Brazilian and Argentine suppliers may require longer lead times due to infrastructure constraints.
2. Oilseed Processing Enterprises
Chinese crushers gain bargaining power through diversified sourcing but must adapt to varying bean quality standards. South American soybeans typically contain higher protein levels (Brazil avg. 37% vs. U.S. 34%), requiring adjustments in blending ratios for meal production. Plants in coastal regions are recalibrating storage cycles to accommodate longer maritime shipments from South America.
3. Logistics and Shipping Providers
The trade shift alters global bulk carrier routes, reducing Panamax vessel demand on Pacific routes while increasing Atlantic basin shipments. Port operators in Argentina's Rosario and Brazil's Santos must handle higher volumes, where congestion could delay turnarounds by 5-7 days during peak seasons.
Key Considerations for Businesses
1. Certification Compliance
Importers should verify Argentina's SAGyP phytosanitary certificates and Brazil's GMO documentation requirements, which differ from U.S. protocols. Some Chinese provincial customs now conduct additional mycotoxin tests for Black Sea-origin shipments.
2. Supply Chain Reconfiguration
Companies relying on just-in-time U.S. soybean deliveries may need to increase safety stocks by 15-20% when switching to South American suppliers due to longer transit times (35-45 days vs. 20-25 days from U.S. Gulf).
3. Contract Structuring
Given currency volatility in Argentina (peso) and Brazil (real), dollar-denominated contracts with price adjustment clauses are becoming essential. Some crushers now include force majeure terms covering South American harvest delays.
Industry Perspective
Analysis suggests this represents more than a temporary market fluctuation. China's establishment of alternative supply channels appears structural, with strategic investments in Brazilian crushing facilities and Ukrainian port infrastructure. The transition may stabilize China's protein supply chain but could increase global price volatility during Southern Hemisphere crop setbacks.
Conclusion
This trade realignment underscores the agricultural sector's growing geopolitical dimensions. While diversification strengthens China's food security, it introduces new variables for global traders - from navigating Argentine export taxes to managing Black Sea shipping risks. Market participants should treat this as an ongoing trend requiring continuous monitoring of crop conditions, trade policies, and logistics bottlenecks across multiple hemispheres.
Source Information
Data sourced from official customs statistics and USDA export reports as of March 26, 2026. Market analysis based on verified industry procurement patterns. Note: Ukraine's export capacity remains subject to Black Sea shipping corridor developments.
Related News
- 00
0000-00
How to Use Agricultural Price Reports to Time Crop Sales and Protect Margins - 00
0000-00
How to Select Hand Horticulture Tools for Pruning, Weeding, and Soil Preparation - 00
0000-00
Do Organic Farming Premiums Justify Higher Sourcing Costs for Exporters? - 00
0000-00
Agricultural Brand Promotion: How Farms Can Build Trust and Win Repeat Buyers - 00
0000-00
How to Evaluate Smart Irrigation Systems for Agriculture by Crop Type and Field Conditions
Agriculture Industry Editorial Team
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.