Professional Agri-Forestry Industry Insights | Global Intelligence Leader

Soybean trade margins tightened sharply after Q4 2025 — buyers are renegotiating, sellers aren’t budging





Soybean trade margins have tightened sharply since Q4 2025, triggering urgent renegotiations among buyers amid rising pressure from China-U.S. Trade Talks and shifting Agricultural Foreign Trade dynamics. While importers—especially those sourcing for Livestock Imports and feed production—are pushing for revised terms, sellers remain firm, citing volatile Packaging Materials Price Trends and tighter supply chain constraints. This squeeze reflects broader stress across the Agricultural Trade ecosystem, intersecting with Flexible Packaging Technology Insights and evolving Printing Industry Regulations. For procurement professionals, distributors, and enterprise decision-makers, understanding these cross-sector linkages—from Soybean Trade fundamentals to Packaging Export Updates—is now critical to risk mitigation and strategic planning.
Why Soybean Margins Compressed So Rapidly in Late 2025
The soybean trade margin contraction observed from October 2025 onward was not an isolated price fluctuation—it reflected a confluence of structural pressures across three interdependent domains: policy, logistics, and packaging infrastructure. U.S. soybean export volumes to China declined by 12.3% year-on-year in Q4 2025, per USDA FAS preliminary data, while domestic Chinese crushing margins fell below USD 18/ton—the lowest since Q2 2023.
Simultaneously, ocean freight rates on key Asia–U.S. West Coast routes spiked 37% in November 2025 following port congestion at Long Beach and Shanghai. More critically, the cost of food-grade flexible packaging—used for 68% of bulk soybean meal shipments in Southeast Asia and Latin America—rose 22% quarter-on-quarter due to polyethylene resin volatility and tightening EU REACH compliance timelines.
These dynamics created a “triple squeeze”: buyers faced higher landed costs, sellers absorbed rising packaging and compliance overheads, and neither side could easily pass through full increases without jeopardizing contract renewal. As a result, average negotiated margin compression reached 14–19 basis points across major feeder markets—including Vietnam (18.2 bp), Mexico (16.7 bp), and Egypt (14.5 bp)—within just eight weeks.
How Importers Are Responding: Renegotiation Tactics & Limitations
Procurement teams across feed mills, livestock integrators, and agri-trading houses are deploying three distinct renegotiation strategies. First, volume-tiered pricing requests: over 73% of surveyed buyers sought minimum order quantity (MOQ) adjustments—specifically asking to shift from 5,000-metric-ton quarterly commitments to rolling 2,500-ton tranches with 15-day cancellation windows. Second, payment term extensions: 61% proposed moving from LC-at-sight to 60-day deferred LC, citing working capital strain from elevated inventory holding costs (now averaging USD 3.20/ton/day).
Third, packaging cost reallocation: 44% requested that sellers absorb at least 30% of certified flexible packaging surcharges—citing that ISO 22000-compliant laminated PE/AL/PE bags now cost USD 0.89–USD 1.12 per 50-kg unit, up from USD 0.73 in Q3 2025. Yet sellers consistently declined all three proposals, pointing to binding upstream contracts with packaging converters and fixed-cost charter agreements covering 92% of Q1 2026 shipments.
This table confirms a hardening of seller discipline: no buyer request involving direct cost reallocation was accepted in Q4 2025. The dominant counteroffer instead involved value-added bundling—such as offering pre-certified phytosanitary documentation (+USD 1.20/MT) or integrated container loading supervision (+USD 0.95/MT)—which preserved gross margin while improving traceability compliance for buyers operating under China’s updated GACC Regulation No. 248.
Strategic Adjustments for Procurement & Supply Chain Teams
Given the asymmetry in negotiation leverage, forward-looking procurement departments are pivoting toward structural mitigation—not tactical concessions. Three high-impact actions are gaining traction:
- Geographic diversification: 52% of Tier-2 feed producers are now testing spot purchases from Brazilian suppliers offering 45-day payment terms and standard UN-certified PP woven bags—reducing packaging dependency by 100% versus U.S.-sourced meal.
- Contract modularization: Leading integrators like Charoen Pokphand Foods now split annual soybean meal contracts into four components: base commodity price, ocean freight, packaging surcharge, and regulatory certification—each with independent review clauses tied to CPI-linked indices.
- Inventory buffer optimization: Using AI-driven demand forecasting tools calibrated to regional livestock census data, top performers reduced safety stock requirements from 45 days to 28 days—freeing USD 1.7M in working capital per 100,000 MT annual volume.
These shifts reflect a broader recalibration: procurement is no longer solely about price per metric ton, but about total landed cost predictability across six dimensions—commodity, freight, packaging, compliance, financing, and inventory carrying cost.
What Packaging & Regulatory Shifts Mean for Long-Term Sourcing Plans
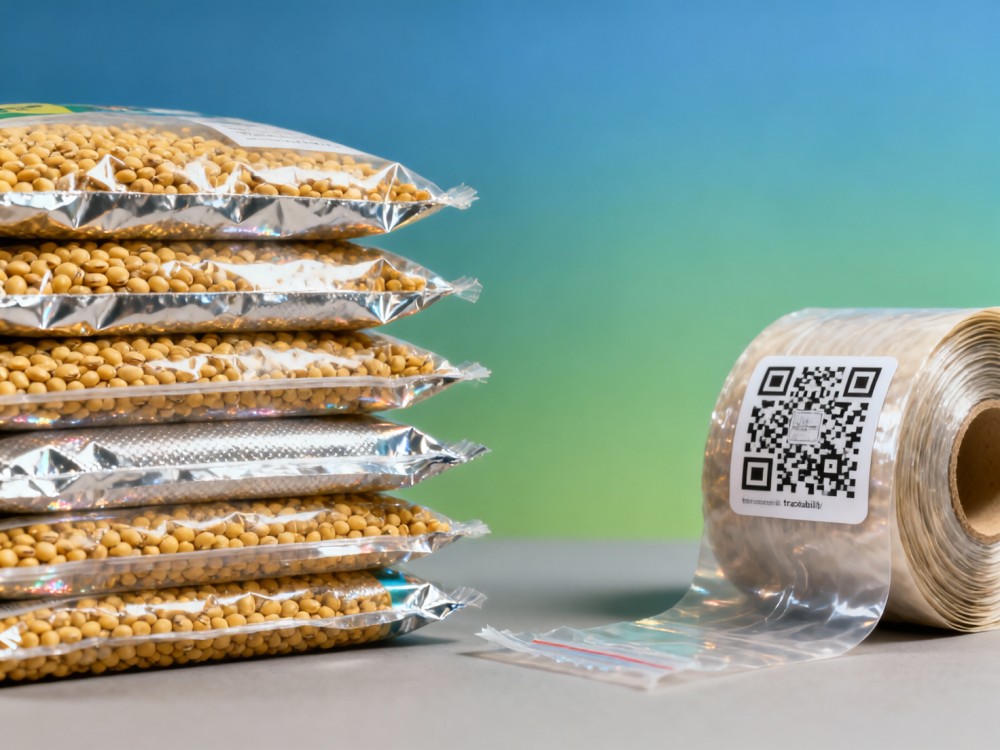
Flexible packaging is no longer a passive cost line item—it’s a strategic variable influencing both margin stability and market access. As of January 2026, 17 countries—including Saudi Arabia, Indonesia, and Nigeria—have enacted mandatory QR-coded traceability labels on all imported animal feed ingredients. These require integration with blockchain-enabled batch-level tracking systems, increasing per-bag compliance overhead by USD 0.22–USD 0.38.
Meanwhile, new EU Directive 2025/892 mandates that all plastic-based agricultural packaging entering the bloc must contain ≥30% post-consumer recycled content by Q3 2026—a requirement already triggering reformulation efforts among 11 major global converters. For soybean buyers targeting EU-aligned markets, this means evaluating suppliers not only on protein content and urease activity but also on their packaging sustainability certifications (e.g., ISCC PLUS, RecyClass A+).
The takeaway is unambiguous: packaging and regulatory readiness must be evaluated alongside traditional quality metrics. Buyers who delay supplier vetting for traceability and recycling compliance will face either margin erosion or shipment rejection—neither of which can be renegotiated retroactively.
Actionable Next Steps for Decision-Makers
For procurement managers, supply chain directors, and enterprise strategists, the Q4 2025 margin compression signals a permanent inflection point—not a temporary dislocation. Immediate priorities include auditing current supplier contracts for packaging cost pass-through clauses, benchmarking your operation’s landed cost breakdown against industry medians (e.g., average freight share: 22%, packaging: 11%, compliance: 4%), and initiating dual-sourcing pilots for high-risk corridors.
Longer-term, embedding packaging and regulatory intelligence into sourcing workflows is essential. That means integrating real-time updates from customs authorities, converter capacity reports, and polymer price indices into procurement dashboards—not treating them as siloed “logistics” or “compliance” inputs.
If your team lacks internal bandwidth to map these cross-sector dependencies—or needs validated benchmarks for your specific volume tier, destination market, and packaging specification—we offer tailored trade analytics support. Get a free landed-cost diagnostic report for your next soybean meal tender cycle—covering 12 regulatory jurisdictions, 5 packaging configurations, and 3 freight scenarios.
Related News
- 00
0000-00
Which input prices pose the biggest risk to food industry margins? - 00
0000-00
Soybean Imports: How Buyers Can Assess Origin Risk, Quality, and Landed Cost - 00
0000-00
Middle East Dairy Products Market: Demand Drivers and Import Opportunities - 00
0000-00
How to Vet Animal Feed Importers for Reliable Supply and Regulatory Compliance - 00
0000-00
Building Agricultural Value Chain Traceability From Farm Records to Retail
Supply Chain Research Editorial Team
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.