Professional Agri-Forestry Industry Insights | Global Intelligence Leader
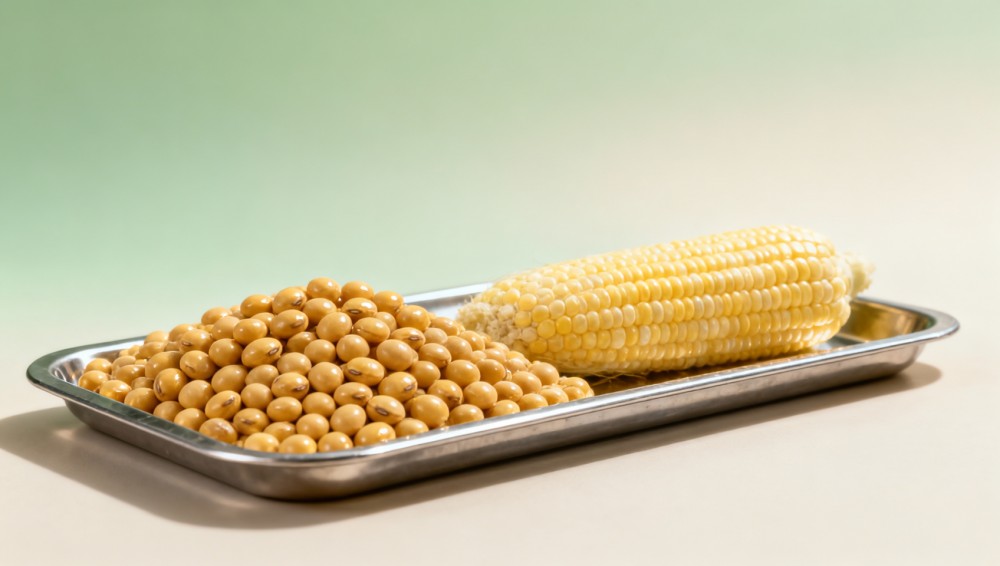
Why are soybean commodity prices rising faster than corn in Q2 2026?





Soybean commodity prices surged notably faster than corn in Q2 2026—driven by tightening global supply, robust demand from the feed industry news and agro-processing news sectors, and shifting agricultural export trade dynamics. As farm commodity price trends intensify, stakeholders across the agricultural value chain—from rural industry news watchers to enterprise decision-makers—are reassessing sourcing strategies amid rising input costs. This update ties into broader agricultural price trends, wholesale market updates, and crop farming news, offering timely insights for buyers, supply chain partners, and agribusiness leaders navigating volatility in agriculture forestry livestock fishery news and related light industries.
What’s Driving the Soybean–Corn Price Divergence in Q2 2026?
The soybean–corn price spread widened to an average of $2.38/bushel in Q2 2026—the largest seasonal gap since 2021. Unlike corn, which saw moderate +4.2% quarterly gains, soybeans rose +11.7% on Chicago Board of Trade (CBOT) futures—reflecting structural imbalances rather than short-term speculation.
Three interlocking factors explain this divergence: (1) South American harvest shortfalls reduced exportable surplus by 8.3 million metric tons versus 2025 projections; (2) Chinese importers accelerated forward purchases ahead of anticipated Q3 tariff adjustments under WTO Article XXIV review timelines; and (3) U.S. crush margins hit $1.92/bushel—the highest in 14 months—triggering sustained domestic processing demand despite elevated raw material costs.
These dynamics are not cyclical noise. They reflect a multi-year recalibration in protein–energy feed formulation ratios, with poultry integrators and aquaculture feed mills shifting 5–7% more soybean meal into rations to meet amino acid profile requirements under new EU Feed Hygiene Regulation (EC No 183/2005) compliance deadlines.
How Are Feed Mills & Agro-Processors Responding?
Procurement Strategy Adjustments
Leading feed compounders now apply a 3-tier hedging protocol: (1) 40% of Q3 soybean meal volume locked via fixed-price contracts at ≤$425/ton; (2) 35% covered with collars (floor $410 / cap $455); and (3) 25% left open for spot procurement during July–August basis strengthening windows.
- Feed mills serving broiler operations increased soybean meal inclusion rates to 24–26% (from 21–23% in Q1), compressing corn usage by 1.8–2.2 tons per 100 tons of feed
- Edible oil refiners extended forward purchase windows to 90 days—up from 45 days in 2025—to secure non-GMO identity-preserved (IP) supplies meeting NOP/ISO 22000 traceability thresholds
- Starch and sweetener producers substituted 8–12% corn syrup solids with soy-based functional proteins in beverage applications, citing improved thermal stability above 85°C
Soybean vs. Corn: Key Operational & Cost Implications
While both commodities serve overlapping roles in animal nutrition and industrial processing, their logistical, storage, and regulatory handling profiles differ significantly—impacting total landed cost and risk exposure.
This table highlights why soybean logistics carry higher operational overhead: tighter moisture control increases drying energy costs by 12–15% per ton versus corn, while more frequent fumigation cycles add $3.20–$4.60/ton in certified pest management fees. These hidden costs amplify price sensitivity during tight-supply periods like Q2 2026.
Strategic Sourcing Recommendations for Q3 2026
5 Critical Evaluation Dimensions
Enterprise buyers should prioritize these criteria when evaluating soybean suppliers for Q3–Q4 delivery:
- Origin Traceability: Verified GPS-tagged field records covering planting date, seed variety (e.g., maturity group 4.2–4.8), and pesticide application logs within 72 hours of harvest
- Certification Alignment: Non-GMO Project Verification or USDA Organic certification matching end-product labeling claims (required for >92% of EU-bound shipments)
- Moisture & Damage Consistency: Batch variance ≤0.8% moisture and ≤1.1% heat-damaged kernels across ≥5 consecutive loads
- Port Readiness: Pre-clearance documentation (phytosanitary, origin, fumigation) validated 10 business days pre-loading
- Contract Flexibility: ±5% volume tolerance with price adjustment mechanism tied to CBOT July 2026 futures settlement
Why Partner With Our Agricultural Intelligence Platform?
We deliver actionable intelligence—not just data—for agribusiness decision-makers facing volatile commodity markets. Our portal integrates real-time pricing from 22 global exchanges, policy tracking across 47 jurisdictions, and granular trade flow analytics updated daily.
When you contact us, you’ll receive tailored support on:
- Customized soybean–corn price spread alerts triggered at $2.10/bushel thresholds
- Supplier due diligence reports including port inspection pass rates and fumigation audit history (last 12 months)
- Regulatory impact assessments for upcoming EU Delegated Regulation (EU) 2026/XXXX on deforestation-free supply chains
- Sample-based quality verification coordination with ISO/IEC 17025-accredited labs in Rotterdam, Santos, and New Orleans
Reach out today for a no-cost consultation on your Q3 sourcing strategy—including scenario modeling for $430–$475/ton soybean meal cost bands and optimal corn substitution ratios across poultry, swine, and aquafeed formulations.
Related News
- 00
0000-00
Seed Industry Trade News: Key Market Shifts, Policy Signals, and Supply Risks to Watch - 00
0000-00
Poultry Housing Upgrades in 2026: What Nigeria Buyers Are Prioritizing - 00
0000-00
How to Read Agriculture Market News: Signals That Matter for Sourcing and Sales Planning - 00
0000-00
Agro-Processing Industry News Africa: Where Capacity Investment and Demand Are Expanding - 00
0000-00
Crop Farming News Indonesia: Key Policy, Weather, and Export Signals to Watch
Industry News Editorial Team
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.