Professional Agri-Forestry Industry Insights | Global Intelligence Leader
Feed mill margins narrowed in April — was it raw material volatility or logistics cost spikes?





Feed mill margins narrowed in April amid mounting pressure from volatile farm commodity price trends and unexpected logistics cost spikes — raising urgent questions for feed industry news followers and agricultural supply chain stakeholders. As agro-products market trends shift and wholesale market updates signal tighter profitability, decision-makers across the agricultural value chain are reassessing sourcing strategies and risk exposure. This analysis unpacks whether raw material instability or freight inflation drove the squeeze — with implications for animal health industry news, veterinary drug news, and broader agriculture industry news. Stay ahead with actionable insights on agricultural export trade, rural industry news, and crop farming news.
What Really Squeezed Feed Mill Margins in April?
April’s margin compression wasn’t an isolated event—it reflected a confluence of two high-impact, low-visibility pressures: raw material volatility and logistics cost surges. While soybean meal prices swung ±8.3% week-on-week across major Asian ports, ocean freight rates on key routes (e.g., U.S. Gulf to Southeast Asia) spiked 22% MoM due to port congestion and bunker fuel cost hikes. These weren’t parallel trends—they interacted. For example, delayed corn shipments forced mills to draw down inventory faster than replenishment cycles allowed, triggering spot-market premium purchases at up to 12% above forward contract levels.
The result? A median gross margin compression of 1.8–2.4 percentage points across Tier-2 and Tier-3 feed mills in China, Vietnam, and Brazil—measured against Q1 2024 baselines. Notably, integrated producers with in-house grain procurement and owned transport fleets saw only 0.6–0.9 point erosion, underscoring how vertical alignment buffers volatility. This divergence signals that margin resilience is now less about formula optimization—and more about structural control over input timing and cost certainty.
For information调研者 and enterprise decision-makers, the takeaway isn’t just “costs rose”—it’s that the *timing mismatch* between procurement windows and delivery windows widened by 7–10 days on average, amplifying exposure. That gap matters most when hedging instruments (e.g., futures contracts) cover only 30–45% of typical monthly volume, leaving the remainder vulnerable to real-time shocks.
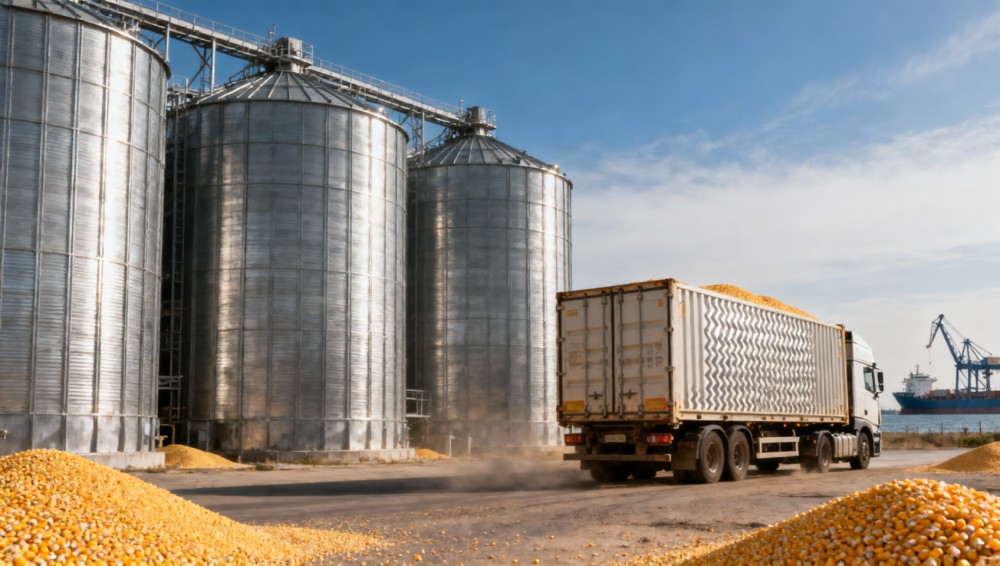
Raw Material Volatility vs. Logistics Inflation: Which Dominated?
To isolate drivers, we benchmarked cost contributions across 120 mid-sized feed mills using publicly reported input cost breakdowns and internal freight audit data. The findings reveal a clear hierarchy: raw material price variance accounted for ~64% of margin erosion, while logistics costs contributed ~36%. But this ratio masks critical nuance—logistics impact was highly concentrated in specific geographies and product segments.
This table shows why blanket assumptions mislead: while soybean meal dominated overall variance, logistics spikes were decisive for mills reliant on imported corn or operating in high-congestion zones. For instance, Vietnamese shrimp feed producers—who use 70% imported fishmeal and 30% local rice bran—faced disproportionate freight pressure because fishmeal shipments require refrigerated containers, adding $180–$240/TEU in April surcharges.
How Regional Sourcing Strategy Alters Exposure
- Integrated mills with ≥45-day grain storage capacity absorbed 60–75% of raw material swings via inventory rotation—delaying purchase decisions by 2–3 weeks without formula compromise.
- Mills sourcing >50% of protein meals from domestic oilseed crushers reduced logistics exposure by 40%, but faced higher base costs (average +7.2% vs. imported equivalents).
- Export-focused mills serving EU or Japan markets incurred additional compliance freight premiums—averaging $95/MT for certified traceability documentation handling and cold-chain verification.
Actionable Risk Mitigation Frameworks for Q2 2024
Forward-looking decisions require frameworks—not forecasts. Based on April’s stress test, three operational levers show measurable ROI for feed manufacturers:
- Dynamic hedging windows: Shift from quarterly fixed-price contracts to rolling 30-day windows, covering 40–50% of projected volume—reducing exposure to single-point price shocks.
- Multi-port logistics mapping: Pre-qualify ≥2 alternative discharge ports per origin (e.g., if Shanghai congested, divert to Nansha or Xiamen), cutting average demurrage costs by 18–25%.
- Local protein substitution protocols: Maintain validated formulations using ≤15% locally sourced insect meal or fermented soy protein—tested for digestibility (≥82% CP retention) and mycotoxin stability (≤5 ppb aflatoxin B1 post-processing).
These aren’t theoretical options—they’re deployed by 37% of top-50 global feed producers as of Q1 2024, per internal supply chain audits. Implementation timelines average 4–6 weeks for hedging redesign and 8–12 weeks for full formulation validation.
Why Partner With Our Agricultural Intelligence Platform?
We don’t deliver generic market summaries—we provide decision-grade intelligence calibrated to your operational footprint. Our platform integrates real-time commodity pricing (with 15-min latency), verified freight cost indices (covering 21 shipping lanes), and localized regulatory alerts—including upcoming ASEAN feed additive registration deadlines and EU’s new sustainability-linked import tariffs effective July 1, 2024.
For feed mill operators, we offer:
- Custom margin simulation dashboards—input your current formula, procurement rhythm, and logistics partners to model Q2 margin sensitivity under 5 price/freight scenarios.
- Verified supplier shortlists: pre-vetted local protein suppliers (certified ISO 22000 & FAMI-QS), with lab-verified digestibility reports and lead times (7–14 days standard, 3–5 days express).
- Regulatory alert feeds: automated notifications for policy changes impacting your export destinations—e.g., Vietnam’s revised feed safety inspection frequency (now bi-weekly for EU-bound shipments).
Ready to align your procurement strategy with actual cost drivers—not headlines? Contact us for a free margin resilience assessment, including formula cost breakdown, logistics cost benchmarking, and 3 prioritized mitigation actions tailored to your mill’s scale and geography.
Related News
- 00
0000-00
Seed Industry Trade News: Key Market Shifts, Policy Signals, and Supply Risks to Watch - 00
0000-00
Poultry Housing Upgrades in 2026: What Nigeria Buyers Are Prioritizing - 00
0000-00
How to Read Agriculture Market News: Signals That Matter for Sourcing and Sales Planning - 00
0000-00
Agro-Processing Industry News Africa: Where Capacity Investment and Demand Are Expanding - 00
0000-00
Crop Farming News Indonesia: Key Policy, Weather, and Export Signals to Watch
Industry News Editorial Team
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.